Private Pension with Gildi
A Private Pension is a great way to build long-term savings that support you throughout life. You can use your savings to buy your first home, pay down your mortgage, or enjoy greater financial freedom from the age of 60.
Apply for a Private Pension
Savings that grow from day one
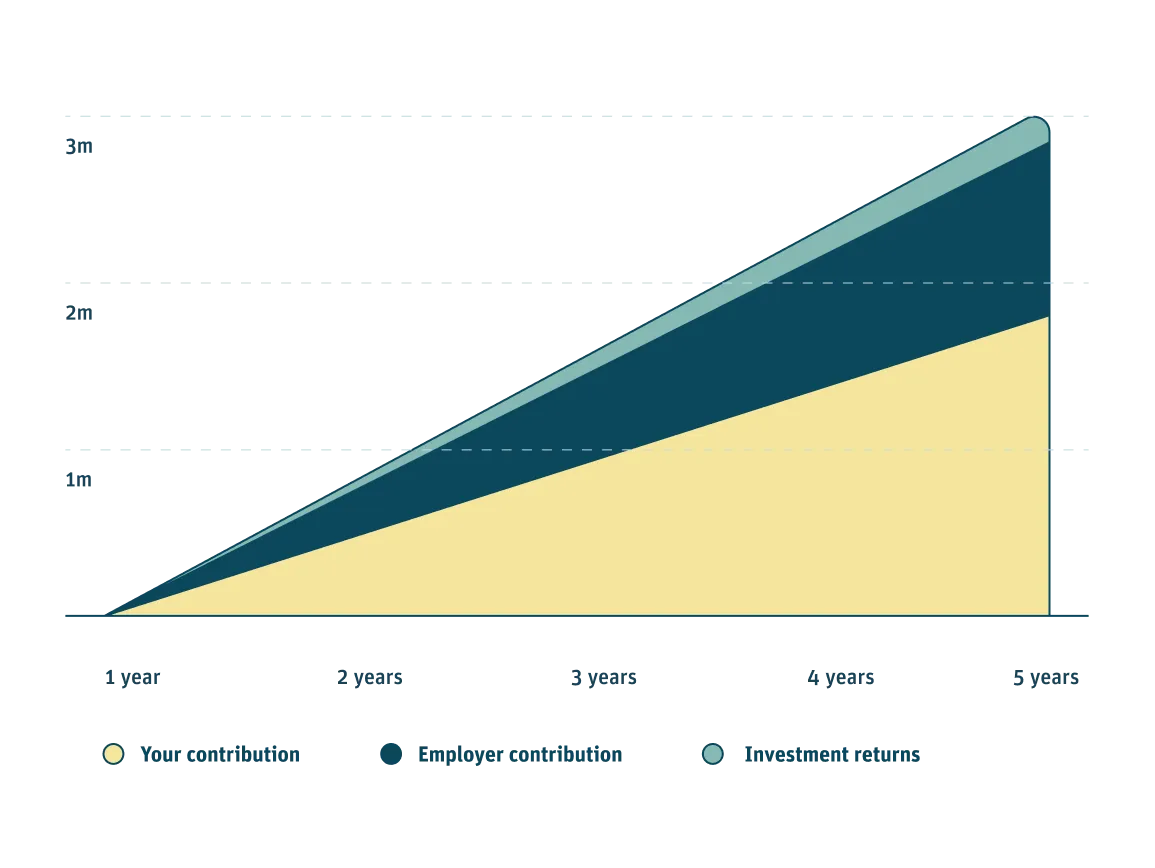
You can contribute up to 4% of your gross salary to a Private Pension. Your contributions are made before tax, and your employer matches them with an additional contribution of up to 2% of your salary – effectively giving you a salary increase that goes straight into your pension.
If you contribute 4% of your salary and your employer contributes 2%, your savings increase by 50% from the very start.
Your path to home ownership
If you are buying your first home – or have not owned one in the past five years – you may be able to use your Private Pension savings for a down payment.
Once you own a home, you can continue to use your Private Pension contributions to make tax-free payments towards your mortgage. This helps you pay off your loan sooner and reduce your monthly repayments over time.
Security for you and your loved ones
Unlike mandatory pension savings, your Private Pension is your personal property and is inheritable. It can provide valuable financial security for your loved ones if something were to happen to you.
Your Private Pension is also protected from creditors, meaning it cannot be claimed if you experience financial difficulties or bankruptcy.
Returns that work for you
Your Private Pension grows over time in line with the investment option you choose, helping your savings build for the future. Unlike most other savings, you do not pay capital gains tax on the investment returns.
How much you save depends on your salary and how much you contribute
Choose the investment option that suits you
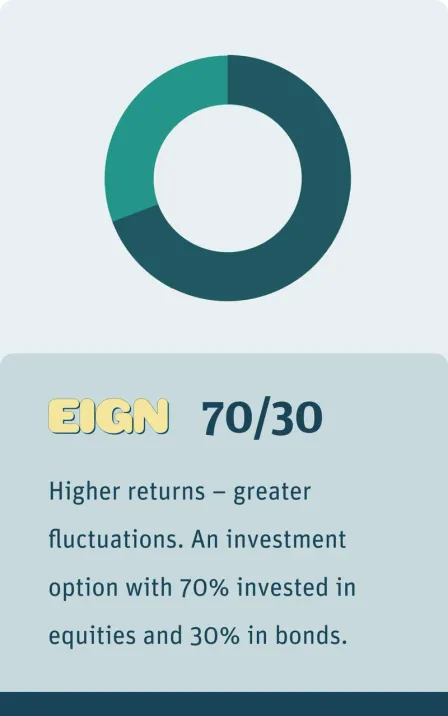
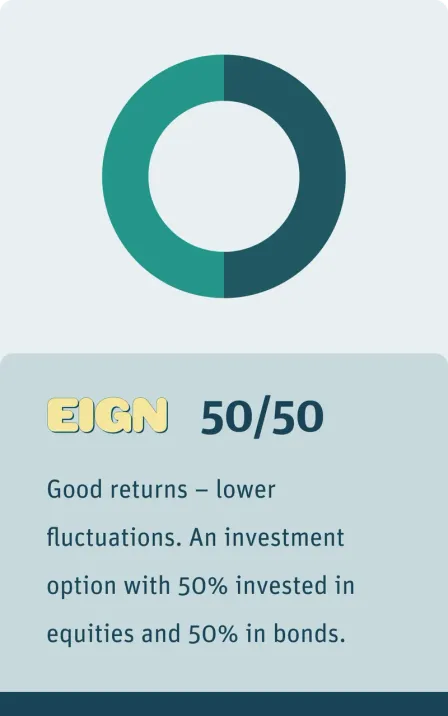
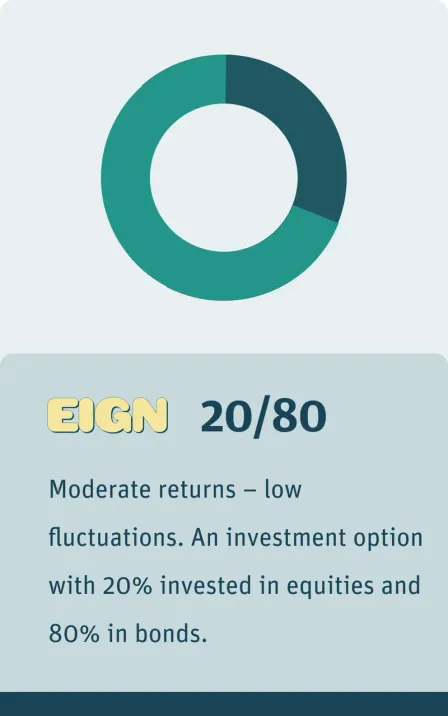
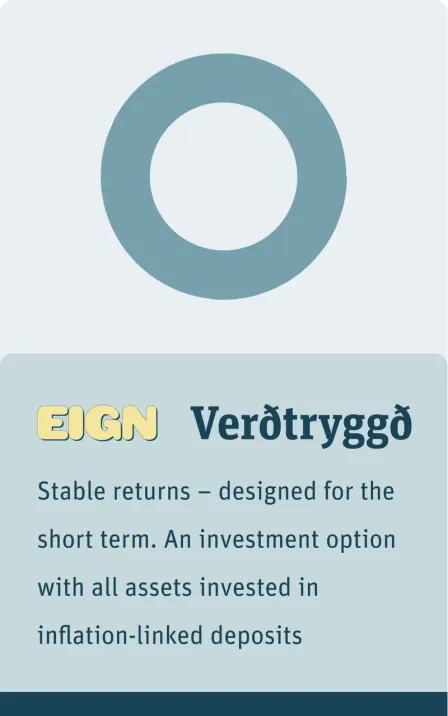
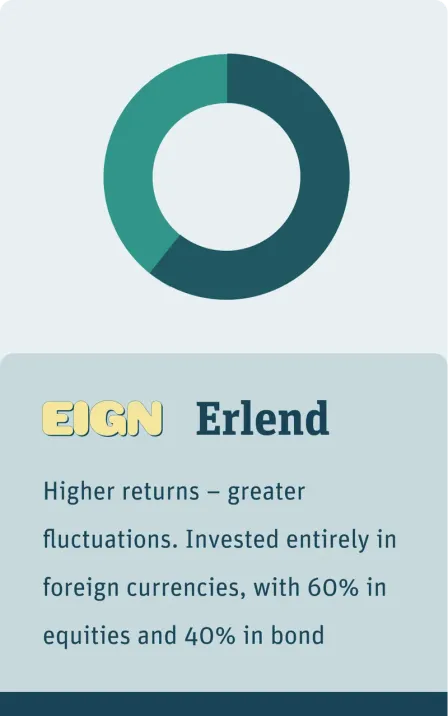
People have different savings goals, so it is important to have a choice of investment options to suit different needs. With Eign, you can choose the investment option that best matches your goals. Higher-risk options may be suitable if you are investing for the long term, while more stable options may be a better fit if you expect to use your savings sooner, for example to buy a home. You can also choose Eign – Aldurstengd, which automatically adjusts your investment strategy as you get older, or Eign – Erlend, which invests in foreign-currency assets and is denominated in euros.
We encourage you to explore the investment options and contact us for personal guidance if you have any questions that are not answered here.